Showing posts with label 401k. Show all posts

Wednesday, March 15, 2017

"Fearless Girl": An Empty Symbol For Misplacing Girls' Aspirations

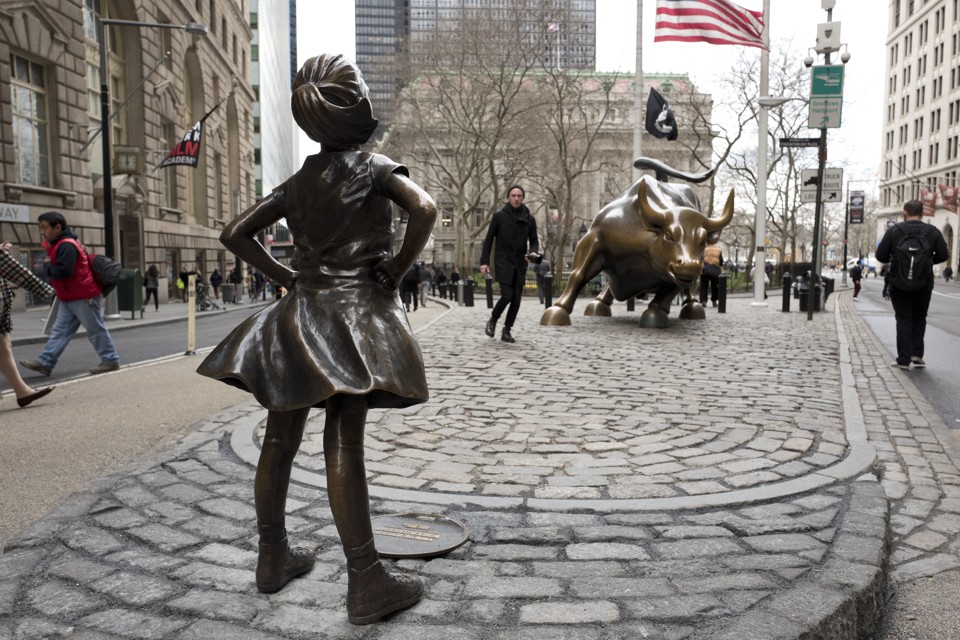
The "Fearless Girl" statue faces down Wall Street's famous Charging Bull.

"That we Americans allot the richest rewards of our economy to speculators, is a question of mores; that we allow one-sixth of our fellow citizens to be ill-housed, ill-clad, and ill-nourished is a question of morals. That we shrink from our problems instead of attacking them with eagerness, generosity and hope is a question of morale. The questions are obviously interrelated." - George P. Brockway, in 'The End of Economic Man - Principles of Any Future Economics', p. 86.

The statue 'Fearless Girl' became an instant icon of women's liberation and strength just hours after  it had been placed in front of the famous Wall Street bull in celebration of International Women's Day. The statue is meant to honor women, specifically those in finance who are "historically forgotten". The problem is that high finance, not only in the U.S. but around the world, has made a veritable mess not only of women's lives but men's as well, namely on "Main Street" and for Main Street priorities. Hence, the statue is really an empty symbol paying homage to a system that has more exploited than helped average Americans.  It may make some little girls feel "fearless" for a bit - staring down that bull  - but in the end Wall Street will have its way and grind everyone under unless it is tamed, regulated.

With the Trumpies ready to water down the fiduciary rule - the one that requires financial advisors to disclose any conflicts of interest - things are not going to change for the better any time soon.

It was George P. Brockway in his 'End of Economic Man' who noted that  ultimately our choice as a society is to reward either markets and speculators or the commonweal based on "Main Street". So far, we've made mainly the wrong choices and allowed the market to dictate our future and quality of life.  This has been from its domination over our health care via shares purchased for various insurance companies, to its yen to replace workers with automation to jack up share price for the benefit of speculators.

And let's also be aware that it is Wall Street that has been pushing incessantly for the privatization of Social Security. One big reason the Street desperately wants Social Security monies in its insatiable maw is that it it's pretty well exhausted the largest (boomer) 401k market - and they'll soon be cashing out, along with their IRAs.

Nowhere is the distortion more evident than in the 401k and investments made there, which puts the ordinary person at great financial risk.  Perhaps the best financial education I ever received, was thanks to William Wolman and Anne Colamosca in their book 'The Great 401k Hoax', (2002), which offered the best advice for recognizing real returns as opposed to the bubble variety. With their solid arguments they showed, for any given fiscal environment, what a realist investor could expect to make. As they noted, one needed to look carefully at the percentage profits returned by X, Y or Z company. If it is averaging 1.3% a year, then that is the real return you can expect.  The stock hawkers bejabber of 10% annualized returns, or more often, 7 percent, is purely designed to lure the unwary into stock investment.

The authors' arguments were further reinforced about 6 years later in a Financial Times article (‘A Metaphorical Proposal’, Mar. 13, p. 11A, 2008) by Michael Skapinker. He cited remarks by Joseph Berardino – chief exec of Arthur Andersen- who noted how the existing reporting system “fails to communicate essential information about the real risks facing companies” to the small investor.  If the small investor doesn't know these risks, how can he make judicious choices? He can't.

Skapinker quoted Berardino as noting how accountants can only issue generic ‘pass’ or ‘fail’ judgments on companies – but never disclose the red ink being bled by a company that’s been passed. (What's referred to as a “bleeding edge” company wherein auditors are actually resigning). As the author notes, to do so would precipitate a collapse in share prices. Duh! (But, tough luck!)


Wolman and Colamosca, meanwhile, paid great attention to how the 401k has been abused and misused, usually by financial shysters - often in workers' companies, but also on the "Street".  Their primary beef? The 401k was never designed as an "investment" vehicle but as a purely savings medium! It was meant to salt your money away in safe, low risk abodes - while being matched by your company to some degree- and all the while not having to pay taxes on it. But almost from the start of the plan, named after the section in the tax code, people -workers were driven to put money into stocks, mainly equities, and other high risk instruments.  Little wonder, that small fry investors in 401ks have been fried and refried, over and over again.

They will be again, as sure as the Sun rises in the morning, once the new stock bubble bursts, as it will. As George Brockway has observed: the purpose of every Bull market is to take back all the gains made, mainly from small investors.  So, why would any little girl want to be part of this system? Why not instead be inspired to be a "fearless climate scientist" or astrophysicist?

As Cara Sheffler of The Guardian recently put it:

"State Street Global Advisors, the investment firm behind the ‘Fearless Girl’ sculpture temporarily placed in front of the famous Wall Street bull, pulled off a formidable marketing coup when they placed the statue there on Women’s Day. But let’s not kid ourselves into thinking that it is a brave feminist statement. It is not.  Fearless Girl doesn’t have to worry about affording college – she’s owned by an investment firm! No one can shut her out of the economy, as so many of her flesh-and-blood sisters have been: she owns Manhattan real estate. In the financial district, no less! No wonder she’s so fearless."

Indeed. And another reason she's so fearless is that she isn't subject to Pareto economics the way the rest of us mortals are. (Nor would any females ensconced in the towers of high finance.)  So it is a fact that with few exceptions, modern economics has dictated we are all subject to the Pareto utility function, to Pareto efficiency:


Basically, we are graphing "utils" or nominal units of "utility" on the vertical axis, vs. value of dollars used or consumed along the horizontal. The curves are displayed for two populations, one "rich" (say earning in the top 1% or $340,000/yr.) and the other "poor" (earning about $14,000/yr.). The key aspect to note is the width corresponding to the "delta x" portion of the gradient (delta U over delta x) which translates into the net dollar's worth for each population. As readers can see from inspection, the width of $1 for the rich is significantly longer than the one for the poor. This translates into the argument that the buck is worth more to the rich man, and hence, any transfer from the rich to the poor hurts the rich more than it helps the poor .

Thus, by Pareto's original example (in quotes): Allowing the wolf in the wolf-sheep combo to EAT the sheep expresses less overall "hurt" or pain on it than permitting the sheep to remain unscathed, thereby merrily prancing away eating its grass while the poor wolf starves. "The wolf" let us again bear in mind in concert with George Brockway's thesis, is the Wall Street paradigm.

The Pareto utility also explains why former Fed Chairman Alan Greenspan went on record in an appearance before congress (in 2003) to assert that "Social Security benefits need to be cut to pay for Bush’s tax cuts."  What on Earth was the man thinking? Well, he's thinking on the basis of Pareto efficiency!    Social Security payments, especially with COLAs, do everything the Fed Chairman didn’t want. They pour more money into the economy, but not via productive labor or market indices, returns. People receive their checks merely by existing and breathing day to day, and having paid into the system with FICA deductions. Even then, they receive far more in benefits than actually paid in, making a total mess of "utils" earned.

"The Street" isn't happy with this set up because it is cut out of the Social security income stream especially via potential juicy fees, commissions.  For example, if these expenses and commissions total 3.5% per annum, half of a 7% return is wiped out, leaving our exuberant investor with only 3.5% takings. If the particular privatized account is "churned" - meaning subjected to lots of internal exchanges and activity - that fee/commission factor could easily become 8%, 10% or more. The person left with virtually NO gain. In a down market this would amount to a nightmare.

What about health care? How does it work under a Pareto system? The clue was revealed by Academic Economist (and former Reagan Advisor) Martin Feldstein, after being awarded the presidency of the American Economic Association in 2004. A large part of his address was devoted to the issue of health insurance. Feldstein made the case that health care is in trouble in this country because deductibles and co-payments are too low, and as a result people (mainly the non-wealthy partially subsidized by health insurance) over use the system and go to the doctor too many times.


Hence, it more redounds to the benefit of shareholders (of stocks in health insurance companies) if a sick person is paid something like $134 not to see a doctor, given each doctor visit (then) costs on average $150. In like manner, the Repuke health plan is designed to benefit stock shareholders by containing and minimizing care rather than expanding it. Hence, the $800 b in cuts to Medicaid by 2020 will achieve Ryan's Randian goal of capping health costs as it "de-federalizes" care.


So why erect a "fearless girl" statue facing the notorious Wall Street Bull and encourage women and girls to entertain becoming fellow shysters to the sharks already there? It makes little sense, not that many of them would anyway. (Hopefully!) I can't imagine thousands of women leaving noble professions like nursing or teaching to become cutthroat shylocks on Maul Street. Or, perhaps I have too much of a 60s perspective.

Cara Sheffler again:

"Having it all” for most women won’t mean being Marissa Mayer or Sheryl Sandberg. The women’s movement, the marches for equality, are not about making every little girl a CEO, but rather about rendering the national dialogue more inclusive. Ironically, womensmarch.com has launched a campaign to convince Americans to divest from banks that support the Dakota pipeline.

Not every person has the option to do so, but women need to divest at a deeper level: we need to divest our values of social equality from Wall Street success. We need to understand that economic justice is not the plot of Working Girl; economic empowerment is not taking a helicopter to East Hampton every weekend during the summer season."

Exactly so. But how many  will process that?  How many women and girls mesmerized by that statue facing the bull will grasp that it likely has little to do with establishing economic justice? How many others will realize that just becoming a broker on Wall Street, where you might try to make a mint or earn vacays to the Hamptons, is not exactly economic empowerment for the many?


Most spot on, she writes:

"Feminism is about human decency, not molding young girls in the image of a banking industry that bets against us, shorts us, and then receives government bailout money.

It’s an industry that always has enough in its coffers to bet on both horses. America has companies on both coasts – on Wall Street and in Silicon Valley – that need to be shamed into civic responsibility, yet demand equal protection before the law. They restructure, outsource and demand tax breaks as job creators. Yet the cities in which they are located squeeze out the middle class and become bedroom communities for their very wealthy employees and clients. "

I could not have put it better, and Ms. Sheffler hits several notes to do with the Pareto model that are important, especially shorting the public then getting bailouts and the gentrification aspect noted at the end. Lastly:

"We need women who will realize new possibilities for companies to work toward the common good, to use capitalism to extend the promises of our founding documents to all, rather than serving as a pernicious, perfectly legal tool of oppression. We need female lawmakers to do that, too.

We need to remember these ladies, and we need symbols that will help us to do so. Some, of course, interpret a little girl staring down the mean, old bull of Wall Street as doing precisely that. But it’s really hard to take on Wall Street when you’re funded by Wall Street. That’s something Fearless Girl is sure to find out ."


Again, why not more inspiration for little girls to become scientists?  There was a lame effort back in 2012 called “Science: It’s a Girl Thing!” . The letter I in “science,”  once one accesses the site,  is a tube of lipstick.   The defense for this vacuous nonsense? Máire Geoghegan-Quinn of the European Commission explained that the campaign was trying to “overturn clichés and show women and girls (and boys too!) that science is not about old men in white coats.”    But that is not the way to do it.

Meanwhile, spokesman Michael Jennings added that the clip was “intended to catch the attention of the target audience – 13-to-17-year-old girls,” in a “fun, catchy” attempt to “speak their language to get their attention.”

Errrr.......you really want to know the best way to get their attention? You detach them from their ipads, iphones, cell phones, and Facebook obsessions then let some intellectual light in. You try to stimulate the radiance of that "light" by encouraging independent inquiry. You don't feed their culturally-biased fantasies with superficial baloney and bunkum.

Nature editor Helen Pearson called it “packed with painful patronizing cliché,” while Victoria Herridge, a paleontologist at Britain’s Natural History Museum, declared it “beyond parody… all the things we worry about with gender stereotyping and body image these days.” Meanwhile, University College London social psychologist Petra Boynton succinctly asked, “For the love of all things holy, what is this crap?”

What is it indeed? Basically, as most of us see it, a case of the "tail wagging the dog". The demeaning, superficial and lowest common denominator culture attempting to entice young females into the rarefied realm of rigorous science....by appealing to lowest common denominator social or personal appearance obsessions.

To me, the "fearless girl" attempt to get more girls into Wall Street finance is no different.  What we need is not more traders,  brokers or hedge funders ensconced on Wall Street but a lot more female scientists, and physicians. Especially with the looming shortage of the latter. And the way to encourage them isn't with tubes of lipstick and vacuous 'fun' themes but getting them excited with the subjects by inspired teaching, or well thought out appeals to girls' intelligence.

Above all, as George Brockway argued in his book, we need to restore the balance between Main Street and Wall Street, not distort it further.


Monday, June 23, 2014

A Retirement Crisis By 2030? It Doesn't Have To Be

In the June 30th  TIME article: '2030 - The Year Retirement Ends' - we are asked to believe the money will have run out for Medicare already (by 2026) and will be three years from doing so for Social Security. "Generation X-ers will begin moving out of work into their Golden Years" - but only to find out they don't have enough money to live on, and will have to return to work - if even as janitors or Walmart greeters.  And as for those Boomers, well they will be getting the last of the good 'pickings' before the Trust Funds run dry.

All of which is nonsense. Indeed, the very thought the richest nation in the world could even allow a "retirement security crisis" to unfold such as TIME described, is absolute balderdash. The only reason it may come to that (since I am not discounting the greed and egos of our politicos) is the willingness to just sit and do nothing. Oh, and by the way, let's eliminate the 'blame the Boomers' bullshit right now. In that case politicos (actually Reagan and the congress) did do something by increasing the FICA taxes specifically to deal with the projected Boomer onslaught. So what happened? The additional money generated was most spent by the Bushies on their wars of choice and tax cuts! But that's not on the Boomers, it's on the Bushies!

The following data shows how much has been raided each year, the data from the Trust Fund administrators and GAO:

Year:  ................Amount raided

2011.................$67.0 billion

2010.................$87.0 billion

2009...............$137.0 billion

2008...............$180.2 billion

2007...............$186.0 billion

2006...............$185.5 billion

2005..............$173.5 billion

2004..............$151.1 billion

2003.............$155.6 billion

2002.............$159.0 billion

2001.............$163.0 billion

2000.............$151.8 billion
----------------------------

TOTAL:  $2.63 TRILLION

Now, any person with a single neuron for a brain would realize that it doesn't matter if you fill a one gallon bucket with a cup every day (equal to 6 oz.) if there are massive holes in the bottom that let out 12 oz. in the same time! 

Thus, the worker-to -beneficiary ratio is a red herring meant to deflect attention from the REAL problem which is the yearly raids on monies received from payroll taxes and intended to go to future beneficiaries! So long as these raids continue unabated, NO solution or "re-tooling" of the program will work, not raising payroll taxes, not making cuts, NOTHING!  The raiding has to stop first.
Despite this, TIME proffers little but the usual, standard "solutions", including:

1) The government should force workers to contribute more to their 401ks

2) The "entitlements" (Social Security and Medicare) need to be "dealt with" and the system changed.

3) People most affected need to work longer.

4) The 401k needs to be re-tooled

Let's take (2) first and why it is wrong. In nearly all cases "entitlement reform" implies cuts (e.g. "chained CPI") not increased benefits, yet is the latter which is needed. First, Social Security and Medicare are NOT "entitlements" because workers have paid into them over 40 years or more. In many cases, the 6.2% payroll tax is the biggest tax hitting most of the working poor. But they do it because down the road, after their backs are nearly broken from toil and their hands can barely grasp a buck from arthritis, they will have some residue of dignity in their old age. Some semblance of financial independence. (TIME also admits that half of all those over 65 today would be poor if Social Security was eliminated.)

Even then, there are no gifts or freebies! The seniors still have to cough up nearly $100 a month for Medicare premiums, which are deducted from their Social Security, making it even less - say if it's the only income they have. Next, we know that Medicare premiums have risen over 136% the past ten years while Social Security cost of living adjustments have increased barely 30% over the same time. In other words, seniors are losing out by having to shell out ever more which one can consider a de facto cut.

Another support aspect the media conveniently forgets, which is dragging us toward a putative crisis, is the $244 billion lost because the payroll taxes were intentionally discontinued for two years. Incredibly, this move was engineered by the Democrats (mostly Neoliberals, to be sure). At the time I wrote several blog posts excoriating them for deliberately undermining Social Security and hence the retirement security of millions, given Boomers were piling into S.S. (According to TIME, by 2012, 13% of all Boomers had signed up for Social Security).

Now let's look at (1). This is a useless solution because in most cases the inability to max out or even contribute to the 401k is because disposable income isn't enough to allow it. After groceries, utilities and mortgage (or rent) all grab their share, workers find there isn't enough left to put aside - given the meager wages too many Americans earn. Hence, having the government force workers to contribute would merely compound the existing outrage of a pathetic national minimum wage. Unless the government -congress increases the minimum wage to a living wage it has no business trying to force workers to save more on any front - whether for health care, or S.S.

As for getting people to work longer (including delaying social security payments until the person turns 70), that's all well and good if they have a comfy job where their aging bodies can withstand more years without excess wear and tear. A writer, for example, will do ok, so will a taste tester, a 'mystery shopper', a librarian, or a food critic.  A heavy laborer (e.g. coal miner), or even a custodian or trash collector, not so much. Hence, it is foolishness to expect any of the latter group to work to 70 or past it. Nor is there a need to ask them if the country infused its social insurance programs with the money needed - or at least stopped the incessant raids!

The last, re-tooling the 401k, is not much of a solution either - given the 401k is in large measure responsible for the whole retirement security problem. As the article notes (p.43):

"The fragility is  in large part due to the massive shifts in the American retirement system since 1980. That's when the 401k plan was invented by a benefits consultant working on a cash bonus scheme for bankers, who had the idea to take advantage of an obscure provision of the tax code - allowing for deferred compensation of individuals to be matched by their company. The result was the 401k, a savings account that lets employees contribute pretax income from their paychecks. But unlike the traditional pension it doesn't promise a specific regular payment on retirement."

The last sentence is most important and what too many Americans fail to grasp. That is, in order to get regular payments per month which would be like the original defined pension - THEY have to create it themselves! That is, they'd have to have saved enough in their 401ks to generate an amount of money to purchase an immediate fixed annuity which in turn will pay them a steady amount monthly.

But let's understand why the 401k was created in the first place: in order to relieve companies of having to shell out defined pensions indefinitely for their employees - thereby cutting into their bottom lines.  Thus, the 401k emerged as a deliberate device to shift risk from corporations to their workers. And hey, if the workers couldn't amass enough - tough luck!

Another factor: most Americans got into trouble with their 401ks by trying to use them as investment vehicles when they were always designed only for conservative savings. Because of this investment meme - pushed also by the companies - workers often lost money when each Bull market came crashing down (as it did in 2008 and as it will again) or when major corrections occurred.

The best expose of this was perhaps by William Wolman and Anne Colamosca in their book 'The Great 401k Hoax', (2002), which offered the best advice on recognizing real returns as opposed to the bubble variety. With their solid arguments they showed, for any given fiscal environment, what a realist investor could expect to make. As they noted, one needed to look carefully at the percentage profits returned by X, Y or Z company. If it is averaging 1.3% a year, then that is the real return you can expect.  The stock hawkers bejabber of 10% annualized returns, or more often, 7 percent, is purely designed to lure the unwary into stock investment.

The authors' arguments were further reinforced about 6 years later in a London Financial Times article (‘A Metaphorical Proposal’, Mar. 13, p. 11A, 2008) by Michael Skapinker. He cited remarks by Joseph Berardino – chief exec of Arthur Andersen- who noted how the existing reporting system “failed to communicate essential information about the real risks facing companies” to the small investor.


Given that most workers already had problems navigating the complex investment choices most companies offered in their 401k plans, it was easily understood how they were set up to lose money.  This suggests that the 401k either needs to be removed, or radically revamped.

If it is removed what will replace it? The best idea yet comes from legislation pushed through by Kevin de Leon of California which would guarantee a living wage to every Californian working in the private sector, on retirement. De Leon's approach, called the CSC or the California Secure Choice Retirement Savings Program, was signed into law in 2012 and combines the best aspects of defined benefit plans with what used to be the 401k.

Another option would be similar to the proposed MyRA of Obama, which would be expanded to let all middle class workers save in a fund administered by the U.S. Treasury. Such a fund would be 'safe' - meaning the risk factors that we now see dogging 401k plans would be eliminated.

Another solution to any future retirement crisis, is to simply raise the income subject to the payroll tax - say from the current $117,000 to $600,000.  This would extend Social security's lifetime to at least 2075 and with a minimum of pain. (Doing the same for the Medicare FICA taxes, as well as increasing their absolute amounts - say to 4.4 percent would do the same.). Keeping the incomes subject to payroll taxes so low is a fool's errand anyway, given that so many of the wealthiest still insist on taking their 'cut' because they "earned it". So why not increase the income level to reflect that? It is pure political chicanery that it hasn't been done up to now!

Lastly, TIME cites experts (e.g. Paul Taylor) who insist communal living of different generations is the answer. Grandma and Gramps can live with their kids, John and Jill (in their 40s) and their own kids- Rudy and Trudy. Well, maybe - maybe not. It depends whether all living under the same roof can get along harmoniously, at least most of the time. But one thing we mustn't do is "force communal living", i.e. by forcing seniors to delay receiving their Social Security until 70 - so they are compelled to live with Junior and wife (and kids) til then.  That draconian solution is so fraught with peril it doesn't need explanation.

What I don't subscribe to is Taylor's glib pronouncement that:

"There's a growing sense, for all the generations, that no one has been spared and everyone has to suffer to some extent".

But it doesn't have to be that way! If the country made the right choices and especially ceased to involve itself in stupid wars and wasteful nation building projects - there'd be enough money to cover the Millennials' student loans, Gramps' medical ills, and John and Jill's mortgage payment.  Also, as I showed above, the less painful solutions are there - but we have to get our cosseted rich folks to sign on to them - in their own interest.

Would these rich folks really want to live in a nation that's being torn apart by revolution similar to what we see in the Ukraine or Iraq? If we aren't prepared to cut back our yen for empire,  or elicit the one percent to contribute to the commonweal, we will see ever more suffering at home....and even....as author David Cay Johnston put it in a recent salon.com interview, civil distress so severe it might even incite a revolution  that will be "the bloodiest the world has ever seen".

(See: http://www.salon.com/2014/05/22/bloodiest_thing_the_world_has_seen_david_cay_johnston_on_inequalitys_looming_disaster/

Instead of bitching about "socialism" and "takers",  the richest need to see their welfare is as much at stake as those deluged by debt and job loss. As John F. Kennedy once put it:

"If a free society cannot help the many who are poor, it cannot save the few who are rich."

See also:
http://www.smirkingchimp.com/thread/richard-eskow/56585/a-secret-plan-to-close-social-securitys-offices-and-outsource-its-work

Monday, May 19, 2014

How Neoliberalism Has Alienated Working Class Young Adults

In the most recent issue of 'Democratic LEFT', the publication of The Democratic Socialists of America, writer Beth Cozzolino examines via book review how the Neoliberal capitalist system has succeeded in crafting "privatized narratives of adulthood" for working class Millennials.  She uses as her incentive and starting point the book by Jennifer M. Silva entitled: 'Coming Up Short: Working Class Adulthood in an Age of Uncertainty' (Oxford University Press.)   This is timely given that the working class youth, as well as middle class, are all adversely affected by Neoliberals' dominating theme of valuing "self-sufficiency over solidarity"

As we know, an overriding solidarity among Millennials is to their benefit - socially and economically - given that shared resources and support systems provide a higher probability not to fail at aspirations or objectives. An experienced cadre of older young people, exposed to the 'System', can then impart lessons and info on exactly how difficult it is to succeed in a rigged economic system which begins with unstated advantages for the scions of inherited wealth.  With this input, the working or middle class youth can then make more realistic life decisions, which redound to their benefit, as opposed to playing into the Neoliberal gamers' paws that 'anything is possible' and all is well. 

The latter is played by Neoliberalism because it makes it easier for youth to accept that their fate is entirely in their hands, and not contingent on blind luck or the mercies of the Neoliberal system. Interestingly, as Cozzolino and Silva appear to suggest, the "anything is possible"  and self-sufficiency ploy works best on working class young adults - who usually have the most to lose. Why is this? Perhaps because many or most of them will not complete college so not be exposed to the critical thinking skills needed to see through Neoliberalism in all its foul facets.


For the working class youth then, there is the lack of critical thinking skills and adequate education, combined with absence of peer-to-peer support systems. The Neoliberal preaches the sermon of self-sufficiency to attain this which later pays off dividends for the Neoliberal state. For example, if working class young adults are discouraged from sharing failed experiences and commiserating with each other, they can't know how the System has taken advantage of them in all its sordid ways. They are expected to suffer in silence and they do. Thus, we have a double whammy: absence of education and critical thinking to see through the Neoliberal façade but also lack of peer support to explain multifold reasons for a person's failure in the rigged, Neolib economic system.


Do most youths even know, for example, that most good jobs advertised are already taken before their ads are even published in the papers or online? The publication is merely a pro forma compliance with existing "rules" that mandate a job's announcement to the public - but the position is already taken by a scion, a crony or his offspring.

The lack of peer to peer information sharing also discourages any coherent organization of the disaffected into powerful groups to inveigh against capitalist, corporate interests. In this way the young and disaffected are kept quiet and the inheritance class of owners needn't fret over them or what they might do. They are harmless because they don't communicate with one other, and basically blame themselves for their failures as opposed to the System.

Ms, Cozzolino also makes another salient point:

"Contemporary global capitalism has allowed firms to embark on a 'privatization of risk' - shifting the burdens of potential illness, unemployment and other unforeseen calamities onto employees. Not only are their employment situations precarious but the weight of these risks discourages working class young adults from embarking on stable relationships. 'Commitment, rather than being a hedge against external risks of the market becomes one demand too many on top of the already excessive demands of the post-industrial labor force' '

Thus, even if a working class young adult does get a job, it more likely becomes an onerous trap than an opportunity. He loads fifty crates a day onto trucks perhaps, but if he mashes his back up from lifting, he'll have to assume most of the medical costs. He can't afford to look for a better job because this is all there is and it pays the rent for a 1-room bedroom in a dump. In this light, getting married or engaged is out of the question, though doubled marital resources might help improve circumstances. Hence, the "privatization of risk" concept. 

But instead, the young adults plod on believing it's all their fault they don't have better digs, or jobs.

The classical and fundamental attribution error: Blame yourselves not the System!

Cozzolino goes on to observe:

"By demonstrating just how far Neoliberalism penetrated our psyches, Silva answers the question of why young people who would seem to benefit from social safety nets and solidarity with others cling so fiercely to Neoliberal ideals of untrammeled individualism and self-reliance."

Why? Because the media in the Neoliberal state widely extols these as assets as opposed to being weaknesses and incapacities.  This works hand in glove with the Neoliberal assertion that people are "responsible for their own economic fortunes or misfortune.". Hence, the emergence of the 401k which effectively privatizes risk of financial loss for retirement to individuals (i.e. if they make the wrong choices). The corporation is thereby spared having to dole out any defined benefits plans as in standard pensions, and doing it for decades after the person has left the work force.

Republicans are fond of blaming the working class (and much of the middle class) for drowning in credit card debt from lavish spending. The truth, as Thomas Piketty's (and Sent. Elizabeth Warren's) research shows is that this debt spending is the direct outcome of a savage economic inequality which has seen the wealthiest grab up the vast proportion of wealth. With so little remaining, as reflected in stagnant wages,  even as costs of food, utilities and rents soar- the hoi polloi are left with little choice other than credit card support. They need additional "income" and this is how they achieve it - since the decent jobs aren't there to provide income sufficiency. 

Thus the entire system has been rigged for failure of most working class families and now, many middle class as well. This is after families, unions, fraternal organizations and other mainstays of working class community have been fractured over the decades under the onslaught of Neoliberal privatization and the stress of economic duress.  Much of this stress could have been relieved if even one tenth the resources plowed into wars of choice had been diverted instead to jobs and social uplift programs. But what have we found? Even in the government jobs have been cut - as in the VA and at the IRS.  No surprise then that the VA isn't able to handle its case loads and keeps too many injured vets waiting for treatment.

Add to this the recent cuts to the Social Security Administration resulting in the shuttering of hundreds of their local offices, making it even more difficult for people to secure benefits - and you have a mounting catastrophe in the making.

Cozzolino also isn't averse to taking on higher education as being part of the problem. She notes that:

"One of the major betrayals Silva's respondents face comes from the institution of higher education. Having heard all their lives that college would help them, they took out significant loans for school but were unable to finish, too often dropping out saddled with student loans debt but no degree."


In other words, the inflated promise of future success enticed millions to take out loans, only to be saddled later by the millstone of debt.  This debt weighs most heavily on working class students - defined as being in that class (according to Silva's definition) if the father did not attend college.'

As I noted in my earlier post on Student Debt Bondage, the outcome for too many is to become indentured servants or bond debtors in the Neoliberal wage slave system. There is little chance of escape from this system unless, as Sent. Elizabeth Warren has noted, the terms and conditions for student loans are made more rational and tolerant of the possibility for economic regression. Thus, ALL loans ought to be forgiven after say ten years, if there is little chance of a student paying them off. Beyond that, we could establish free education like other advanced nations (who regard it as a right, not a privilege)  or offer to pay off all university expenses at completion of a degree if the student agrees to some form of particular service or national service. For example, one might have his Bachelors degree paid for if he or she agrees to volunteer two years in Peace Corps or 'Teach for America'.

In this way young adults, especially of the working class, might be liberated economically so they are free to make wider choices for the betterment of the society - including being able to make long term commitments to each other for marriage. In this way, a more stable long term society is assured- as opposed to one in which unit strives against every other leading to chaos and satisfaction of pure self interest.

Is there hope for escape and working class reconstruction in Neolib America? Silva is decidedly negative and "allows little room for the possibility that working class people can live meaningful lives and have fulfilling relationships."

In other words, misery and loneliness are their lot unless they can somehow break out of their addictions and the Neoliberal matrix which holds them in thrall.  But for that, they must be able to see their situation from without and that means making common cause with one another as opposed to seeing peers as opponents for diminishing resources.

It also means transcending the Neoliberal edict of self-sufficiency and radical independence, which too many have swallowed without adequate thought.

The better solution? It's for all classes to come together and coherently act to remove the yoke of Neoliberalism from our midst,. But..... that implies evicting all the politicians who adhere to the Neoliberal idiom and imperative. To accomplish that our entire 'pay to play' political system has to be replaced.


Henry Giroux's blog on 'Protesting Youth in an Age of Neoliberal Savagery'  has it exactly right:

"As the latest stage of predatory capitalism, neoliberalism is part of a broader economic and political project of restoring class power and consolidating the rapid concentration of capital, particularly financial capital (Giroux 2008; 2014). As a political project, it includes “the deregulation of finance, privatization of public services, elimination and curtailment of social welfare programs, open attacks on unions, and routine violations of labor laws” (Yates 2013). As an ideology, it casts all dimensions of life in terms of market rationality, construes profit-making as the arbiter and essence of democracy, consuming as the only operable form of citizenship, and upholds the irrational belief that the market can both solve all problems and serve as a model for structuring all social relations. As a mode of governance, it produces identities, subjects, and ways of life driven by a survival-of-the fittest ethic, grounded in the idea of the free, possessive individual, and committed to the right of ruling groups and institutions to exercise power removed from matters of ethics and social costs. As a policy and political project, it is wedded to the privatization of public services, the dismantling of the connection of private issues and public problems, the selling off of state functions, liberalization of trade in goods and capital investment, the eradication of government regulation of financial institutions and corporations, the destruction of the welfare state and unions, and the endless marketization and commodification of society.

Neoliberalism has put an enormous effort into creating a commanding cultural apparatus and public pedagogy in which individuals can only view themselves as consumers, embrace freedom as the right to participate in the market, and supplant issues of social responsibility for an unchecked embrace of individualism and the belief that all social relation be judged according to how they further one’s individual needs and self-interests. Matters of mutual caring, respect, and compassion for the other have given way to the limiting orbits of privatization and unrestrained self-interest, just as it has become increasingly difficult to translate private troubles into larger social, economic, and political considerations. As the democratic public spheres of civil society have atrophied under the onslaught of neoliberal regimes of austerity, the social contract has been either greatly weakened or replaced by savage forms of casino capitalism, a culture of fear, and the increasing use of state violence."


Young people, especially, must become aware of this blight on people and the planet, and be prepared to flight it to their last ounce of breath!


Stay tuned!

Friday, April 5, 2013

"Well Off" Seniors - And Maybe Why the 401k Needs to be Abolished.

Perhaps the most superlative financial education I ever received, was thanks to William Wolman and Anne Colamosca in their book 'The Great 401k Hoax', (2002), which offered the best advice on recognizing real returns as opposed to the bubble variety. With their solid arguments they showed, for any given fiscal environment, what a realist investor could expect to make. As they noted, one needed to look carefully at the percentage profits returned by X, Y or Z company. If it is averaging 1.3% a year, then that is the real return you can expect.  The stock hawkers bejabber of 10% annualized returns, or more often, 7 percent, is purely designed to lure the unwary into stock investment.

The authors' arguments were further reinforced about 6 years later in a London Financial Times article (‘A Metaphorical Proposal’, Mar. 13, p. 11A, 2008) by Michael Skapinker. He cited remarks by Joseph Berardino – chief exec of Arthur Andersen- who noted how the existing reporting system “fails to communicate essential information about the real risks facing companies” to the small investor.

Skapinker quoted Berardino as noting how accountants can only issue generic ‘pass’ or ‘fail’ judgments on companies – but never disclose the red ink being bled by a company that’s been passed. (What's referred to as a “bleeding edge” company wherein auditors are actually resigning). As the author notes, to do so would precipitate a collapse in share prices. Duh! (But, tough luck!)

And yet, dear readers, that is the blind financial world that 401k investors are bid to enter. And that more of them will be pushed into if Obama goes ahead and makes the "Chained CPI"  for Social Security a reality (See, e.g. http://www.nytimes.com/2013/04/05/us/social-programs-face-cutback-in-obama-budget.html?src=rechp&_r=0  )

Wolman and Colamosca, meanwhile, paid great attention to how the 401k has been abused and misused, usually by financial shysters - often in workers' companies, but also on the "Street".  Their primary beef? The 401k was never designed as an "investment" vehicle but as a purely savings medium! It was meant to salt your money away in safe, low risk abodes - while being matched by your company to some degree- and all the while not having to pay taxes on it. But almost from the start of the plan, named after the section in the tax code, people -workers were driven to put money into stocks, mainly equities, and other high risk instruments.  Little wonder, that small fry investors in 401ks have been fried and refried, over and over again. Under such conditions, the small investor risks his money and security, by investing in ANY non-FDIC insured monetary device


Michael Lind's recent account in salon.com of how the 401k emerged from the reluctance of companies to offer defined benefits plans, should also be required reading for any small scale person - i.e. not of the 1 percent or even of the 10 percent. Lind points out that when Social Security was created in 1935 it was never intended to be the sole means of support for retirees, and the expectation was that employers would make up the difference by providing decent pensions. I mean REAL pensions! Not artificial devices where workers had to save on their own.

As Lind observes:

"The number of private sector workers with defined benefit pensions has fallen from around 40 percent in 1980 to a mere 15 percent today. At the same time, among public sector workers, poor management by state governments, combined with years of economic trouble, has created a crisis for public pension systems in many states.


In order to save money and shift risks to individual workers, employers in the last generation have been switching from defined benefit plans to defined contribution plans like 401Ks. 401K retirement plans and other defined contribution plans, including individual retirement accounts (IRAs), now cover about 42 percent of the workforce as opposed to only about 17 percent in 1979."

Lind adds:

"In these defined contribution plans, savings by individual workers received favorable tax treatment. But the risks, including risks from poor investments and the chance that you will retire during a stock market downturn, fall entirely on the individual. Even worse, many working-class and middle-class Americans with 401Ks are stealthily fleeced by money managers, who charge high and often difficult-to-find fees for allocating retirement money among stocks, bonds and other assets."

Well, this introduces the argument of why have these mutant  contribution "pension" plans at all? IS this the best we can do? Look at this fact, given by Lind:  "One in four Americans, lacking other liquid savings, has been forced to pay for emergencies by withdrawing prematurely from 401Ks or other retirement accounts."

And bear in mind, if that money isn't paid back in a timely fashion there's an enormous tax hit. No surprise, as Lind notes,"the failure of the private alternates like defined benefit pensions and 401Ks has made Social Security by far the most important source of income for most American retirees." 

He notes that according to the U.S. Social Security Administration in 2101, 84.3 percent of the income for Americans over 65 in the bottom income quintile comes from Social Security. Even for the middle quintile, Social Security provides 65.7 percent. Meanwhile, for my wife an myself, it provides roughly 45%. Even then, some maniac pundits consider us "well off" (Yeah, right - assuming one or both of us doesn't get Alzheimers and end up in a nursing home at $3,600 a month!)

One of these nuts is Neoliberal columnist Robert Samuelson. In a notorious column from last year ( 'Well Off Seniors Can Live Well With Less', The Denver Post Business section, May 15, p. 2K),  he argued that:

"trimming benefits for well off seniors isn't just budget arithmetic, it's the right thing to do."


This, of course, brings up the question of how he defines a "well off senior". The first impression I had, without further reading, was one that had an ostensible income of say $250,000/ year (mainly from a defined benefit pension) and also had amassed a net worth of at least $2 million. But on perusing the piece, I saw I was totally wrong and Samuelson's threshold was much, much lower. This then presents a problem if Samuelson's base argument is that "Government over-subsidizes the affluent elderly".

Samuelson began by referencing the government's defined "poverty line" of $12,968 for 2009 for an over-65 couple. Let me say first that, as with the Bureau of Labor Statistics unemployment rate, this income level is low-balled, and I'd say deliberately. By lowballing the poverty line it translates into the government having to do much less for citizens in need, including for an array of benefits such as food stamp qualifications, Medicaid and so forth. But anyone who's done any economics knows this number is farcical. Indeed, its been unchanged since ca. 1969 when the value of the dollar was at least 4 times greater. Hence the more plausible poverty line for a couple today would be around $48,000/year. However, we will go with the lower level of $38,000/yr. advanced by the Economic Policy Institute. The point is, Samuelson's entire specious arguments rests upon an ab initio lowballed number, from which he can lowball all this thresholds of what defines an "affluent senior".

(By contrast, Lind's sober and rational definition of 'well off' senior applies only to the top two income quintiles, the income categories in which are found almost all American political donors, politicians, pundits, journalists and policy wonks. For these rarefied folks Social Security provides a mere 17.3 percent  of the total income for members of the top quintile and a microscopic smidgen (3%) for elderly members of the 1 percent. So it's no wonder these are the jackasses who are salivating most over the Chained CPI).


Back to Samuleson's piece, in which he stated:


"The proportion of elderly living in the high income group- defined as four times the poverty line or almost $52,000 for a couple in 2009- rose from 18.4% in 1980 to 30.6% in 2007"


But again, this is neither here nor there. As I showed, the REAL poverty line, not the lowballed farce, is more like $38,000/yr. even if we are very conservative (since factoring in inflation since 1969 I computed $48,000/yr which $52,000/yr. is barely above). Even at $38,000/yr. this means the retired couple at $52,000/yr. is only one major calamity away from indigence since it's barely 36% above the true poverty line. Indeed, most financial columnists writing on retirement incomes (e.g. in Smart Money magazine last issue), place a couple over 65 with $50,000/yr. income as just barely in the middle class!  AARP statistics, meanwhile, show this amount is firmly within the third quintile or the 'middle of the middle'. It's still a long freaking way from how the well off senior category that Lind defines lives! (The middle of the 2nd quintile, for example, starts at abbout $79,000/yr.)

Samuelson compounded his defective perceptions (which he obviously hopes to pass on to an untutored American population) by invoking "net worth". He writes:


"In 2007, the median net worth (that is assets minus debts) of 65-plus households was $237,000, or about twice the amount of households aged 45 to 54. Among 65-plus married couples, median net worth was $385,000"


 Again,  this misses the point! All it really shows is that the average American of whatever age group is a terrible saver, and this is most likely based on wage scales that have declined absolutely since 1973 - coupled with increased dollar value debasement. To get a more realistic picture, recall net worth factors in the home as well, and we do know most over 65's own their homes. (Which is a move also heartily recommended by financial planners). Let's say the home is nominally worth $100,000 then subtract to get the actual monetary net worth, which turns out to be $137,000 for the average over-65 household and $285,000 for married couples. But this is nothing! Given current over-65s are already advised to have on hand $225,000 to cover expenses and co-pays Medicare won't! That already eats up the total net worth in real money terms of the average over-65'er and most of the net worth (79%) of the married couples! So WTF does Samuelson want? For our "affluent" or "higher income" seniors to live off cat food, along with no vacations ever, and no amenities, period? A life little better than a peon's with no frills, not even minor luxuries? What, is he fucking nuts?

Again, turning to the expert columnists in niche financial magazines, including Smart Money, Money as well as Forbes, the general consensus is that for a senior couple to be able to live comfortably they will need a net worth of at least $1 million, minus the home value! Along with Social Security, according to this lot, they should be able to arrive at an income of at least $75,000 a year! Once more, we see that Samuelson is being dishonest in how he portrays the conditions, but we can't be amazed because they are based on dishonest government definitions, first of the poverty line for couples, and then for the "high income" definition based on this spurious poverty line.

Samuelson's other stat is more or less correct, to wit that ""for the poorest two-fifths of seniors Social Security provides 83% of their income"


But again, that merely shows the desperation of the bottom two quintiles, not that the next highest quintile is living on Easy Street! It shows, indeed, that the bottom two quintiles are living right at the knife edge of imminent poverty, homelessness or worse. Every American ought to be outraged at this, and not merely use it as a basis to take all seniors down to the lowest common denominator - which would indeed happen if Samuelson's plans were implemented.

Perhaps unwittingly, Samuelson provides - by his misuse of economic statistics- the best argument to support Michael Lind's case that we need to EXPAND Social Security, and either cut back or eliminate the 401k. Or, perhaps most sensibly, leave it exclusively for the wealthiest who have the means to sustain market -equity losses over and over, as well as tolerate the highly overcharged fees from 401k plan managers.

But for most little guys, unless they are firmly into safe vehicles like money funds or such, and get their main gains from employer matches only, 401ks are a terrible idea.

Obama, take note! And don't go through with that silly-ass, betraying plan to cut Social Security via the back door! We don't want NO "superlative" Chained CPI, or "semi-superlative". And for christ's sake already, stop bargaining with yourself when  the Repukes aren't even on board!