"That we Americans allot the richest rewards of our economy to speculators, is a question of mores; that we allow one-sixth of our fellow citizens to be ill-housed, ill-clad, and ill-nourished is a question of morals. That we shrink from our problems instead of attacking them with eagerness, generosity and hope is a question of morale. The questions are obviously interrelated." - George P. Brockway, in 'The End of Economic Man - Principles of Any Future Economics', p. 86.
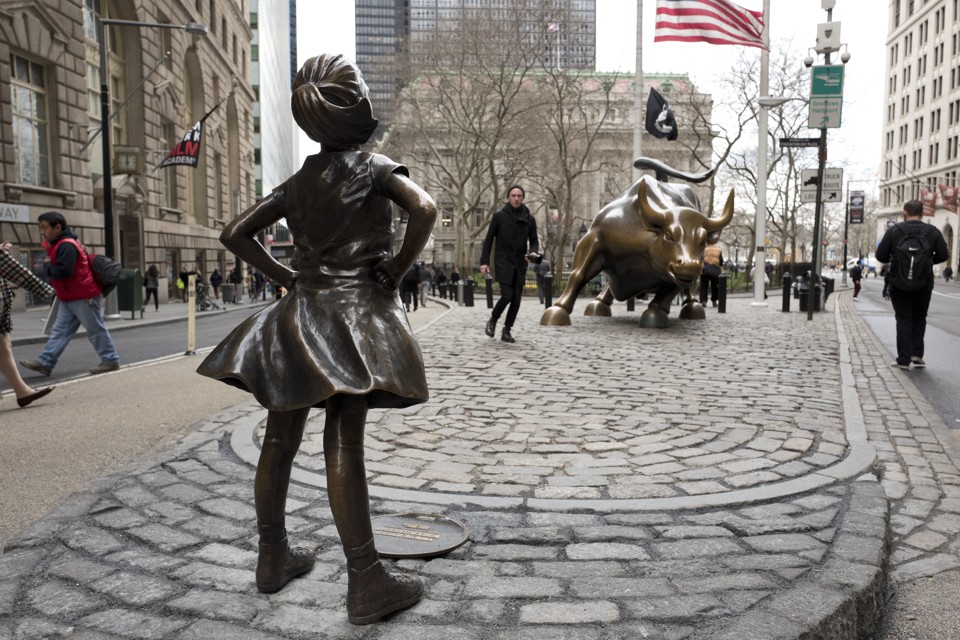
The statue 'Fearless Girl' became an instant icon of women's liberation and strength just hours after it had been placed in front of the famous Wall Street bull in celebration of International Women's Day. The statue is meant to honor women, specifically those in finance who are "historically forgotten". The problem is that high finance, not only in the U.S. but around the world, has made a veritable mess not only of women's lives but men's as well, namely on "Main Street" and for Main Street priorities. Hence, the statue is really an empty symbol paying homage to a system that has more exploited than helped average Americans. It may make some little girls feel "fearless" for a bit - staring down that bull - but in the end Wall Street will have its way and grind everyone under unless it is tamed, regulated.
With the Trumpies ready to water down the fiduciary rule - the one that requires financial advisors to disclose any conflicts of interest - things are not going to change for the better any time soon.
It was George P. Brockway in his 'End of Economic Man' who noted that ultimately our choice as a society is to reward either markets and speculators or the commonweal based on "Main Street". So far, we've made mainly the wrong choices and allowed the market to dictate our future and quality of life. This has been from its domination over our health care via shares purchased for various insurance companies, to its yen to replace workers with automation to jack up share price for the benefit of speculators.
And let's also be aware that it is Wall Street that has been pushing incessantly for the privatization of Social Security. One big reason the Street desperately wants Social Security monies in its insatiable maw is that it it's pretty well exhausted the largest (boomer) 401k market - and they'll soon be cashing out, along with their IRAs.
Nowhere is the distortion more evident than in the 401k and investments made there, which puts the ordinary person at great financial risk. Perhaps the best financial education I ever received, was thanks to William Wolman and Anne Colamosca in their book 'The Great 401k Hoax', (2002), which offered the best advice for recognizing real returns as opposed to the bubble variety. With their solid arguments they showed, for any given fiscal environment, what a realist investor could expect to make. As they noted, one needed to look carefully at the percentage profits returned by X, Y or Z company. If it is averaging 1.3% a year, then that is the real return you can expect. The stock hawkers bejabber of 10% annualized returns, or more often, 7 percent, is purely designed to lure the unwary into stock investment.
The authors' arguments were further reinforced about 6 years later in a Financial Times article (‘A Metaphorical Proposal’, Mar. 13, p. 11A, 2008) by Michael Skapinker. He cited remarks by Joseph Berardino – chief exec of Arthur Andersen- who noted how the existing reporting system “fails to communicate essential information about the real risks facing companies” to the small investor. If the small investor doesn't know these risks, how can he make judicious choices? He can't.
Skapinker quoted Berardino as noting how accountants can only issue generic ‘pass’ or ‘fail’ judgments on companies – but never disclose the red ink being bled by a company that’s been passed. (What's referred to as a “bleeding edge” company wherein auditors are actually resigning). As the author notes, to do so would precipitate a collapse in share prices. Duh! (But, tough luck!)
Wolman and Colamosca, meanwhile, paid great attention to how the 401k has been abused and misused, usually by financial shysters - often in workers' companies, but also on the "Street". Their primary beef? The 401k was never designed as an "investment" vehicle but as a purely savings medium! It was meant to salt your money away in safe, low risk abodes - while being matched by your company to some degree- and all the while not having to pay taxes on it. But almost from the start of the plan, named after the section in the tax code, people -workers were driven to put money into stocks, mainly equities, and other high risk instruments. Little wonder, that small fry investors in 401ks have been fried and refried, over and over again.
They will be again, as sure as the Sun rises in the morning, once the new stock bubble bursts, as it will. As George Brockway has observed: the purpose of every Bull market is to take back all the gains made, mainly from small investors. So, why would any little girl want to be part of this system? Why not instead be inspired to be a "fearless climate scientist" or astrophysicist?
As Cara Sheffler of The Guardian recently put it:
"State Street Global Advisors, the investment firm behind the ‘Fearless Girl’ sculpture temporarily placed in front of the famous Wall Street bull, pulled off a formidable marketing coup when they placed the statue there on Women’s Day. But let’s not kid ourselves into thinking that it is a brave feminist statement. It is not. Fearless Girl doesn’t have to worry about affording college – she’s owned by an investment firm! No one can shut her out of the economy, as so many of her flesh-and-blood sisters have been: she owns Manhattan real estate. In the financial district, no less! No wonder she’s so fearless."
Indeed. And another reason she's so fearless is that she isn't subject to Pareto economics the way the rest of us mortals are. (Nor would any females ensconced in the towers of high finance.) So it is a fact that with few exceptions, modern economics has dictated we are all subject to the Pareto utility function, to Pareto efficiency:

Basically, we are graphing "utils" or nominal units of "utility" on the vertical axis, vs. value of dollars used or consumed along the horizontal. The curves are displayed for two populations, one "rich" (say earning in the top 1% or $340,000/yr.) and the other "poor" (earning about $14,000/yr.). The key aspect to note is the width corresponding to the "delta x" portion of the gradient (delta U over delta x) which translates into the net dollar's worth for each population. As readers can see from inspection, the width of $1 for the rich is significantly longer than the one for the poor. This translates into the argument that the buck is worth more to the rich man, and hence, any transfer from the rich to the poor hurts the rich more than it helps the poor .
Thus, by Pareto's original example (in quotes): Allowing the wolf in the wolf-sheep combo to EAT the sheep expresses less overall "hurt" or pain on it than permitting the sheep to remain unscathed, thereby merrily prancing away eating its grass while the poor wolf starves. "The wolf" let us again bear in mind in concert with George Brockway's thesis, is the Wall Street paradigm.
The Pareto utility also explains why former Fed Chairman Alan Greenspan went on record in an appearance before congress (in 2003) to assert that "Social Security benefits need to be cut to pay for Bush’s tax cuts." What on Earth was the man thinking? Well, he's thinking on the basis of Pareto efficiency! Social Security payments, especially with COLAs, do everything the Fed Chairman didn’t want. They pour more money into the economy, but not via productive labor or market indices, returns. People receive their checks merely by existing and breathing day to day, and having paid into the system with FICA deductions. Even then, they receive far more in benefits than actually paid in, making a total mess of "utils" earned.
"The Street" isn't happy with this set up because it is cut out of the Social security income stream especially via potential juicy fees, commissions. For example, if these expenses and commissions total 3.5% per annum, half of a 7% return is wiped out, leaving our exuberant investor with only 3.5% takings. If the particular privatized account is "churned" - meaning subjected to lots of internal exchanges and activity - that fee/commission factor could easily become 8%, 10% or more. The person left with virtually NO gain. In a down market this would amount to a nightmare.
What about health care? How does it work under a Pareto system? The clue was revealed by Academic Economist (and former Reagan Advisor) Martin Feldstein, after being awarded the presidency of the American Economic Association in 2004. A large part of his address was devoted to the issue of health insurance. Feldstein made the case that health care is in trouble in this country because deductibles and co-payments are too low, and as a result people (mainly the non-wealthy partially subsidized by health insurance) over use the system and go to the doctor too many times.
Hence, it more redounds to the benefit of shareholders (of stocks in health insurance companies) if a sick person is paid something like $134 not to see a doctor, given each doctor visit (then) costs on average $150. In like manner, the Repuke health plan is designed to benefit stock shareholders by containing and minimizing care rather than expanding it. Hence, the $800 b in cuts to Medicaid by 2020 will achieve Ryan's Randian goal of capping health costs as it "de-federalizes" care.
So why erect a "fearless girl" statue facing the notorious Wall Street Bull and encourage women and girls to entertain becoming fellow shysters to the sharks already there? It makes little sense, not that many of them would anyway. (Hopefully!) I can't imagine thousands of women leaving noble professions like nursing or teaching to become cutthroat shylocks on Maul Street. Or, perhaps I have too much of a 60s perspective.
Cara Sheffler again:
"Having it all” for most women won’t mean being Marissa Mayer or Sheryl Sandberg. The women’s movement, the marches for equality, are not about making every little girl a CEO, but rather about rendering the national dialogue more inclusive. Ironically, womensmarch.com has launched a campaign to convince Americans to divest from banks that support the Dakota pipeline.
Exactly so. But how many will process that? How many women and girls mesmerized by that statue facing the bull will grasp that it likely has little to do with establishing economic justice? How many others will realize that just becoming a broker on Wall Street, where you might try to make a mint or earn vacays to the Hamptons, is not exactly economic empowerment for the many?
Most spot on, she writes:
"Feminism is about human decency, not molding young girls in the image of a banking industry that bets against us, shorts us, and then receives government bailout money.
It’s an industry that always has enough in its coffers to bet on both horses. America has companies on both coasts – on Wall Street and in Silicon Valley – that need to be shamed into civic responsibility, yet demand equal protection before the law. They restructure, outsource and demand tax breaks as job creators. Yet the cities in which they are located squeeze out the middle class and become bedroom communities for their very wealthy employees and clients. "
I could not have put it better, and Ms. Sheffler hits several notes to do with the Pareto model that are important, especially shorting the public then getting bailouts and the gentrification aspect noted at the end. Lastly:
"We need women who will realize new possibilities for companies to work toward the common good, to use capitalism to extend the promises of our founding documents to all, rather than serving as a pernicious, perfectly legal tool of oppression. We need female lawmakers to do that, too.
We need to remember these ladies, and we need symbols that will help us to do so. Some, of course, interpret a little girl staring down the mean, old bull of Wall Street as doing precisely that. But it’s really hard to take on Wall Street when you’re funded by Wall Street. That’s something Fearless Girl is sure to find out ."
Again, why not more inspiration for little girls to become scientists? There was a lame effort back in 2012 called “Science: It’s a Girl Thing!” . The letter I in “science,” once one accesses the site, is a tube of lipstick. The defense for this vacuous nonsense? Máire Geoghegan-Quinn of the European Commission explained that the campaign was trying to “overturn clichés and show women and girls (and boys too!) that science is not about old men in white coats.” But that is not the way to do it.
Meanwhile, spokesman Michael Jennings added that the clip was “intended to catch the attention of the target audience – 13-to-17-year-old girls,” in a “fun, catchy” attempt to “speak their language to get their attention.”
Errrr.......you really want to know the best way to get their attention? You detach them from their ipads, iphones, cell phones, and Facebook obsessions then let some intellectual light in. You try to stimulate the radiance of that "light" by encouraging independent inquiry. You don't feed their culturally-biased fantasies with superficial baloney and bunkum.
Errrr.......you really want to know the best way to get their attention? You detach them from their ipads, iphones, cell phones, and Facebook obsessions then let some intellectual light in. You try to stimulate the radiance of that "light" by encouraging independent inquiry. You don't feed their culturally-biased fantasies with superficial baloney and bunkum.
Nature editor Helen Pearson called it “packed with painful patronizing cliché,” while Victoria Herridge, a paleontologist at Britain’s Natural History Museum, declared it “beyond parody… all the things we worry about with gender stereotyping and body image these days.” Meanwhile, University College London social psychologist Petra Boynton succinctly asked, “For the love of all things holy, what is this crap?”
What is it indeed? Basically, as most of us see it, a case of the "tail wagging the dog". The demeaning, superficial and lowest common denominator culture attempting to entice young females into the rarefied realm of rigorous science....by appealing to lowest common denominator social or personal appearance obsessions.
What is it indeed? Basically, as most of us see it, a case of the "tail wagging the dog". The demeaning, superficial and lowest common denominator culture attempting to entice young females into the rarefied realm of rigorous science....by appealing to lowest common denominator social or personal appearance obsessions.
To me, the "fearless girl" attempt to get more girls into Wall Street finance is no different. What we need is not more traders, brokers or hedge funders ensconced on Wall Street but a lot more female scientists, and physicians. Especially with the looming shortage of the latter. And the way to encourage them isn't with tubes of lipstick and vacuous 'fun' themes but getting them excited with the subjects by inspired teaching, or well thought out appeals to girls' intelligence.
Above all, as George Brockway argued in his book, we need to restore the balance between Main Street and Wall Street, not distort it further.

